The Best Things in Life Are Not Free: What’s In Your Wallet?

We’ve all heard it said, “The best things in life are free.” Love is free. Joy is free. Connection is free. But let me gently challenge that idea. The best things in life may begin freely, but they are never sustained without investment, and if you want to know what someone truly loves, don’t listen to what they say. Look at their calendar. Look at their energy. Look at their bank statements. Because where your wallet is, there your heart is also.

Love Is a Verb — Not a Vow

You can tell your spouse, “I love you.” You can tell your children, “You mean everything to me.” But if your spending patterns consistently say something else, that’s the real declaration.

Your finances tell a story. Do they tell a story of devotion? Or distraction? Do they reflect intentional provision and shared experiences? Or private indulgences and hidden priorities?

Money is not evil. Money is not spiritual. Money is directional. It flows toward what you value most.

What Do Your Bills Really Represent?

When someone says, “I have to pay bills,” I sometimes respond gently:

Yes. But what do those bills represent?

    • Are they aligned with your family’s long-term security?
    • Or are they payments on lifestyle inflation?
    • Are they debt tied to ego purchases?
    • Are they funding vices that come before connection?
    • Are there expenditures your partner doesn’t know about?

Let’s be honest. Hidden spending is hidden loyalty. If you are hiding expenses, you are not protecting peace — you are protecting preference, and preference always reveals priority.

Debt as a Reflection of Devotion

Not all debt is irresponsible. Some debt is strategic.

But ask yourself:

Is your debt serving your family — or stealing from it?

If your income increases and your family doesn’t feel more secure, more connected, more resourced — then the money is flowing elsewhere. That “elsewhere” is your functional love.

I say this not as a judge, but as someone who has lived long enough to see the pattern repeatedly. Where money consistently goes, affection eventually follows.

Vices Before Vows

I have worked with executives who claimed their family was everything — yet spent thousands monthly on habits that kept them emotionally unavailable.

    • Alcohol.
    • Gambling.
    • Secret subscriptions.
    • Impulse technology upgrades.
    • Luxury self-rewards that no one else shares.

You can call it stress relief, or you can call it self-care, but if it consistently outranks your partner’s needs or your children’s opportunities, it is not relief; it’s replacement, and the people you love can feel it. They may not articulate it financially, but they feel it emotionally.

The Undisclosed Expenditure Problem

One of the fastest ways to erode intimacy is financial secrecy. Not because of the dollar amount, but because of the divided allegiance. If you are spending money your partner doesn’t know about, ask yourself why.

Transparency builds trust. Secrecy builds suspicion, and suspicion slowly replaces tenderness.

So What Can You Do?

If you are reading this and feeling a little uncomfortable, good. Discomfort is awareness waking up.

Here are some practical, grounded ways to realign your wallet with your heart:

1. Conduct a 90-Day Love Audit

Print your last three months of bank and credit card statements.
Circle:

        • Family investment (education, experiences, shared goals)
        • Security (savings, insurance, long-term planning)
        • Personal indulgence
        • Hidden or unexplained spending

Do not judge yourself. Just observe, and the patterns reveal truth.

2. Create a “Love Allocation” Line Item

Instead of waiting for leftover money to bless your family, reverse it.

Create a monthly category called:

Family Experience & Future Fund

This could include:

        • Weekend trips
        • Educational enrichment
        • Date nights
        • Family goals
        • College savings
        • Shared dream projects

Fund it first. What you fund first is what you value most.

3. Eliminate One Vice Before It Eliminates Connection

Pick one recurring expense that does not strengthen your marriage, your children, or your household stability.

Cut it.

Redirect those funds intentionally.

When your partner sees that shift, trust increases, and when your children feel it, security increases.

4. Schedule a Financial Transparency Conversation

No accusations. No defensiveness. Just:

“What does our spending say about what we love?”

Let that question sit between you. It is powerful.

5. Replace Consumption with Creation

Many indulgent expenses are boredom disguised as reward.

What if instead of consuming more, you created more?

        • A shared side business.
        • A family garden.
        • A home project done together.
        • A learning fund.
        • A family book club.

Investment builds memory. Consumption builds clutter.

When Someone Asks, “Who Do You Love?”

Imagine this.

Someone looks at your finances, without hearing your words.

Would they say:

“Yes. This person loves their family.”

Or would they say:

“This person loves comfort.”
“This person loves escape.”
“This person loves status.”

The best things in life are not free.

They cost:

        • Attention.
        • Intention.
        • Sacrifice.
        • Transparency.
        • Consistency.

Love is not expensive, but misaligned priorities are.

You do not need more income to demonstrate love. You need clearer alignment. Because in the end, your children will not remember what you said. Your spouse will not remember what you declared. They will remember what you invested, and where your wallet is, there your heart will be also.

 

Flip the Script: What Would You Do with That Kind of Wealth?

Have you ever caught yourself shaking your head at the ultra-rich? Maybe you’ve quietly resented Alice Walton, Jeff Bezos, or Elon Musk as if their success somehow stole from your potential. Or perhaps you’ve cast side-eyes toward Mukesh Ambani’s billion-dollar home in India, wondering, “Why does one man need all that?”

If that’s where your mind goes, I get it. I really do. It’s easy to believe that wealth equals corruption, that success on that level could only be achieved through exploitation, dishonesty, or selfishness. But here’s the uncomfortable truth:
That mindset is the very thing keeping you stuck.

The Wealth Trap You Don’t Even See

Money isn’t evil. People aren’t automatically corrupt because they have more commas in their bank account than you. In fact, some of the wealthiest individuals on the planet are using their resources to heal the world, create opportunity, and build legacies of goodness that will last for generations.

Let’s look at some examples:

Prominent Billionaire Philanthropists & Their Contributions

Name Estimated Wealth Primary Business Philanthropic Focus
Elon Musk $250+ billion Tesla, SpaceX Climate tech, space exploration, disaster relief, AI safety through the Musk Foundation.
Jeff Bezos $200+ billion Amazon Bezos Earth Fund (climate change), Day 1 Fund (homelessness, early childhood education).
Larry Page $100+ billion Google Clean energy innovation, global health, and sustainability efforts (some anonymously funded).
Sergey Brin $100+ billion Google Neurological disease research, poverty alleviation, and environmental protection.
Michael Bloomberg $100+ billion Bloomberg LP Public health, climate action, gun safety, and education through Bloomberg Philanthropies.
Warren Buffett $130+ billion Berkshire Hathaway Co-founder of The Giving Pledge, pledging 99% of his wealth to health, poverty alleviation, and education causes.
Mark Zuckerberg & Priscilla Chan $120+ billion Facebook / Meta Chan Zuckerberg Initiative: science, education, criminal justice reform, and immigration reform.
Mukesh Ambani $116+ billion Reliance Industries (India) Education, healthcare, rural development, and digital connectivity through Reliance Foundation.
Alice Walton $70+ billion Walmart Crystal Bridges Museum of American Art; regional health and arts access.
Philip & Penelope Knight $40+ billion Nike Health sciences, cancer research, athletics, and higher education (University of Oregon, Stanford).
Jim & Marilyn Simons $30+ billion Renaissance Technologies (hedge funds) Math education, autism research, basic science research, and environmental conservation.
MacKenzie Scott $30+ billion Amazon (divorce settlement) Unrestricted grants to nonprofits supporting racial equity, education, LGBTQ+ rights, and public health.
Ray Dalio $20+ billion Bridgewater Associates Mental health, education, social justice, and ocean conservation through Dalio Philanthropies.
Dustin Moskovitz & Cari Tuna $20+ billion Facebook, Asana Good Ventures & Open Philanthropy: effective altruism, animal welfare, and existential risk reduction.
Laurene Powell Jobs $14+ billion Apple (Steve Jobs’ widow) Emerson Collective: education, immigration, journalism, environment, and social entrepreneurship.
Pierre Omidyar $8+ billion eBay Omidyar Network: human rights, tech for social good, financial inclusion, and democracy-building.
David Geffen $7+ billion Media & Entertainment Arts & culture institutions, medical research, and HIV/AIDS programs.
Paul Tudor Jones II $7+ billion Tudor Investment Corp. Robin Hood Foundation (NYC poverty), wildlife conservation, and educational access.
George Soros $6+ billion personal (gave away $32+ billion) Hedge Funds (Soros Fund Management) Open Society Foundations: human rights, democratic governance, and education globally.
Reed Hastings $5+ billion Netflix Education reform, expanding access to quality schools, and technology in education.
Howard Schultz $3+ billion Starbucks Veteran services, small business support, racial equity, and youth employment.
John & Laura Arnold $3+ billion Hedge Funds (Enron, Centaurus) Public policy reform, criminal justice, childhood nutrition, and education.
Oprah Winfrey $3+ billion Media & Entertainment Girls’ education in South Africa, disaster relief, poverty alleviation, and wellness initiatives.
Ted Turner $2+ billion CNN, Media Environmental preservation, United Nations Foundation, and nuclear disarmament.
Strive Masiyiwa $1.8+ billion Econet Wireless (Zimbabwe) Education scholarships, healthcare access, and rural electrification across Africa.
Gordon & Betty Moore (Estate) ~$8 billion (estate) Intel The Moore Foundation: science research, environmental conservation, and patient care improvements.
Charles Koch $50+ billion Koch Industries Criminal justice reform, poverty alleviation, and education (controversial due to parallel political funding).

Key Insights from This List:

    • The wealthiest people in the world are increasingly turning to philanthropy, seeing their fortunes as a tool for solving global-scale challenges.
    • They cover wide areas of impact: healthcare, climate change, education, freedom of information, and poverty alleviation.
    • Wealth is not bound by geography: Mukesh Ambani is transforming India’s digital landscape, while Strive Masiyiwa is improving education and energy access in Africa.
    • You could be next. Start where you are. Build what you can. Grow your impact.

Are there wealthy people who misuse their money? Of course. But there are also countless poor people who do the same with the little they have. Wealth magnifies what’s already inside you. If you are generous, wealth gives you greater reach. If you are selfish, wealth only enlarges your selfishness.

Flip the Script: What Would You Do with That Kind of Wealth?

Ask yourself:
If I had Alice Walton’s billions, what good could I do?
If I had Mukesh Ambani’s resources, how would I change my community? My country? The world?
If I suddenly had $100 million, who would I help? What systems would I build?

Stop cursing the rich and start preparing your own life to be a blessing at a higher financial level.


Break Through Your Self-Induced Glass Ceiling

Wealth flows where it is welcomed and respected—not where it is feared or demonized. Here are a few steps to shift your energy and open the door to greater financial prosperity:

  1. Bless Instead of Curse

Next time you see a wealthy person, bless them in your mind. Thank them for what they are doing with their money—even if you disagree with them. Send them love and gratitude for showing you what’s possible.

  1. Heal Your Money Wounds

Many of us grew up hearing phrases like “money is the root of all evil” or “rich people are greedy.” Challenge those childhood beliefs. Money itself is neutral. It’s the energy we bring to it that determines its impact.

  1. See Money as Energy

Money is energy. It is an exchange of value. When you increase your own value—whether through skills, service, creativity, or leadership—you naturally attract more wealth into your life. Energy flows where your focus goes.

  1. Imagine the Greater Good You Could Do

Sit down and dream big. What causes stir your heart? What change would you fund? Start writing your prosperity vision today.

  1. Take Inspired Action

Don’t just sit and meditate on money—go do the work. Build something. Serve someone. Solve a problem in the marketplace. Money follows value.


It’s Time to Stop Getting in Your Own Way

The only difference between you and the ultra-wealthy is mindset, action, and time. You don’t need to be another Alice Walton or Mukesh Ambani. But you can become the wealthiest version of YOU, someone who creates ripples of love, abundance, and transformation in your circle of influence.

So stop hating wealth.
Start honoring what it could become in your hands.
And step boldly into the prosperous future that is waiting for you.


Remember:

It’s not about the Benjamins. It’s about the energy of love, service, and expansion that flows through how the money is used.

The question is, will you allow it to flow through you?

Dream Stealers: Will Block Your Progression to a Better Life

For those seeking a successful lifestyle, individuals often find themselves navigating through various avenues and opportunities. However, a silent adversary can block your progression to a better life. For instance, the concept of indicators that represent living beyond one’s means, which I call “Dream Stealers,” have crept into one’s lifestyle, hindering financial growth and preventing individuals from seizing opportunities for advancement.

Picture this scenario: a millionaire entrepreneur is searching for a business partner. As they drive through a prospective candidate’s neighborhood, they note the lavish homes and expensive cars lining the streets. While these outward displays of wealth may seem impressive at first glance, to the discerning eye of the millionaire, they raise red flags.

Living beyond one’s means often entails maintaining an unsustainable lifestyle based on income or financial resources. Indicators of Dream Stealers could include:

    • Purchasing a home or vehicle that stretches the limits of affordability.
    • Frequent extravagant spending.
    • Accumulating debt to finance a lavish lifestyle.

While it may provide temporary gratification, it sets a dangerous precedent that can have long-term repercussions.

From the millionaire’s perspective, these outward displays of wealth may signal a potential partner is overly reliant on external resources rather than building their financial foundation. The millionaire may view such individuals as liabilities rather than assets, as their lifestyle choices could hinder their ability to contribute meaningfully to a business relationship.

One such entrepreneur pointed to a prospective partner’s car and said, “That could have opened a profitable coffee stand or been the down payment on a business investment that could be providing passive income to support his family better.” Whether true or not, not having an adequate investment portfolio to support his car and home caused the entrepreneur to conceive that this individual was a poor risk or may have some exposure to criminal elements.

Consider the implications for the millionaire entrepreneur: if they were to enter into a partnership or a relationship with someone living beyond their means, it could jeopardize their financial stability and inhibit their ability to grow their wealth. Instead of focusing on seizing opportunities for investment and advancement, they would be burdened with supporting a partner who needs help to sustain their lifestyle.

Furthermore, the millionaire may recognize that individuals who live beyond their means are less likely to prioritize financial responsibility and long-term planning, posing a risk to the success of the partnership or relationship and the overall economic health of both parties involved.

Dream Stealers undermine the potential for mutual growth and prosperity by fostering a mindset of dependence rather than independence. They create a barrier to financial success by diverting resources towards sustaining an extravagant lifestyle rather than investing in opportunities for advancement.

It’s highly beneficial to surround oneself with individuals with similar values and priorities regarding financial responsibility. By forming partnerships and relationships with people who prioritize financial independence and growth, individuals can create a support system that encourages wise decision-making and mutual advancement.

You don’t have to be a millionaire to realize the importance of remaining vigilant and discerning when evaluating potential partners or opportunities. While outward displays of wealth may be impressive, true compatibility and potential for growth lie in shared values, goals, and a commitment to financial responsibility.

Top 10 Signs of Dream Stealers

    1. Living in a home or driving vehicles that appear significantly beyond their means.
    2. Frequent displays of extravagant spending on luxury items or experiences.
    3. High debt levels relative to income, especially if used to finance a lavish lifestyle.
    4. A lack of financial discipline, such as impulse buying or inability to budget responsibly.
    5. Prioritizing appearances and outward displays of wealth over long-term fiscal stability.
    6. Reluctance or inability to discuss financial matters openly and transparently.
    7. Dependence on others for financial support or assistance in maintaining their lifestyle.
    8. Limited savings or investments for future financial security.
    9. Resistance to constructive feedback or advice regarding financial responsibility.
    10. A pattern of seeking instant gratification rather than investing in long-term goals or opportunities.

In contrast, here are behaviors that may indicate an individual could be a better business risk:

Top 10 Indicators of a Good Business Risk

    1. They demonstrate financial prudence by living within their means and maintaining a balanced lifestyle.
    2. They make informed and strategic financial decisions based on long-term goals and priorities.
    3. They invest in personal and professional development to enhance their skills and knowledge.
    4. They have a track record of responsible financial management, including saving and investing for the future.
    5. Being open and transparent about their financial situation and receptive to feedback or advice.
    6. They exhibit a strong work ethic and commitment to achieving success through hard work and dedication.
    7. They are building a network of trusted advisors and mentors who provide guidance and support in achieving their goals.
    8. Display resilience and adaptability in the face of challenges or setbacks, demonstrating the ability to navigate financial obstacles effectively.
    9. Maintain a healthy balance between work and personal life, prioritizing relationships and well-being alongside professional pursuits.
    10. Continuously seek opportunities for growth and advancement, personally and professionally, while remaining grounded and focused on long-term success.

It’s important to note that these are general indicators and should be considered within individual circumstances and specific business or personal relationships. A comprehensive assessment of someone’s financial habits, values, and goals is necessary to determine whether they are a good fit for a business partnership or investment opportunity.

Is There Hope for One Who Suffers from the Dream Stealers Lifestyle?

Changing a lifestyle surrounded by Dream Stealers can be challenging. Still, with dedication and determination, individuals can transform themselves into a better risk and embody a powerfully self-propelled and upwardly mobile personality. Here are some strategies to consider:

Assess Current Habits and Mindset:

Start by reflecting on current habits, attitudes, and beliefs about money and success. Identify any patterns of overspending, reliance on external validation, or fear of failure that may block your success.

Set Clear Financial Goals:

Define specific, measurable, and achievable financial goals that align with your values and aspirations. Whether it’s paying off debt, building an emergency fund, or investing for the future, having clear objectives will provide direction and motivation for change.

Create a Budget and Stick to It:

Develop a respectable budget that outlines your income, expenses, and savings goals. Take the effort to monitor your spending and adjust your budget as needed to ensure you’re living within your means and prioritizing essential expenses over discretionary ones.

Cultivate Financial Discipline:

Practice discipline in your spending habits by distinguishing between wants and needs. Prioritize essential expenses and avoid impulsive purchases or unnecessary luxuries that detract from your long-term financial goals.

Educate Yourself About Personal Finance:

Make a concerted effort to educate yourself about personal finance including such topics as budgeting, saving, investing, and debt management. Use resources such as books, online courses, or financial advisors to enhance your knowledge and skills.

Surround Yourself with Successful Personalities: You can attract genuine success by osmosis. Seek out individuals who embody the traits and values you aspire to cultivate. Surround yourself with positive influences supporting your financial growth journey and encourage responsible decision-making. 

Practice Self-Reflection and Accountability:

Regularly evaluate your progress towards your financial goals and hold yourself accountable for your actions. Be honest about areas where you may fall short and identify improvement strategies.

Adopt an Upwardly Growth-Oriented Mindset:

Adopt an upwardly growth-oriented mindset that views obstacles and setbacks as opportunities with hidden messages leading to a higher understanding and growth. Embrace failure as a natural part of the journey towards success and remain resilient in the face of obstacles.

Take Calculated Risks:

Investigate vistas outside of your comfort zone and be willing to take calculated risks. This builds courage and exposes you to increased potential for moving you to an increased financial set point. Whether starting a new business venture, pursuing a career change, or investing in growth opportunities, be strategic in your decision-making and assess the potential rewards against the risks involved.

Celebrate Milestones and Create a New Financial Set Point:

Recognize and celebrate your achievements and reset your financial set point along the way. Acknowledge your progress towards your financial goals and use it as motivation to attain a new level of financial frequency.

By implementing these strategies and consciously changing your habits and mindset, you can transform yourself into a better risk and embody a powerfully self-propelled and upwardly mobile personality. Remember that change takes time and persistence, but with diligence, dedication, and determination, you can create a brighter financial future for yourself.

The concept of Dream Stealers serves as a cautionary tale against the dangers of living beyond one’s means. By prioritizing financial responsibility, cultivating relationships with like-minded individuals, and remaining discerning in their pursuits, individuals can overcome the influence of Dream Stealers and carve out a new path to long-term financial success and prosperity.


Action of Attraction: The Power of You Not Chasing Abundance

These days, people are obsessed with the hustle—juggling multiple jobs, working long hours, and chasing every opportunity in the name of success. Society has conditioned us to believe that more effort equals more results, that if we just grind harder, push further, and sacrifice more, we will finally reach financial freedom and fulfillment.

But here’s the truth: hustling harder does not guarantee abundance. In fact, constantly chasing money and success often leads to burnout, stress, and a deeper feeling of lack. The belief that you must do more to receive more only reinforces the idea that you don’t already have enough.

But what if the key to abundance isn’t in doing more—but in being more?

The Shift from Scarcity to Abundance

There are two ways people approach life: from a mindset of scarcity or a mindset of abundance.

    • Scarcity mindset: “I need to work harder to make more money.”
    • Abundance mindset: “Money flows to me with ease because I am aligned with abundance.”

People operating in scarcity are always chasing—working long hours, scrambling for more clients, saying yes to every opportunity out of fear that something better won’t come along. This desperation stems from an internal belief that there is never enough: not enough time, money, love, or opportunity.

But when you shift into true abundance, you stop chasing. You trust that the universe is always working in your favor. You no longer feel the need to force or struggle because you know that everything naturally flows to you.

Your Energy Is Your Greatest Currency

Your energy—your thoughts, emotions, and beliefs—determines what you attract. If your energy constantly says:

    • I’m struggling.”
    • “I need more money.”
    • “I have to work harder to succeed.”

Then you are telling the universe: “I don’t have enough.” And because the universe mirrors your internal state, it responds by giving you more struggle, more scarcity, more reasons to believe you have to work even harder.

But when you shift into the frequency of abundance—when you trust that money flows easily, that opportunities are already aligning for you, that you are supported—you stop chasing and start attracting. The universe matches your belief, and suddenly, things begin to flow effortlessly.

Are You Hustling or Are You Aligned?

If you’re constantly exhausted, burnt out, and feeling like you’re never doing enough, you are likely caught in hustle mode instead of abundance mode.

Signs You’re in Hustle Mode:

    • You constantly feel pressure to work harder.
    • You say yes to everything out of fear of missing out.
    • You feel anxious when you’re not being productive.
    • You equate your worth with how much you accomplish.
    • You feel stuck in cycles of financial struggle.

Signs You’re in Abundance Mode:

    • You trust that opportunities come to you naturally.
    • You make decisions from a place of confidence, not fear.
    • You attract financial abundance with ease.
    • You set boundaries and prioritize your well-being.
    • You feel peace and certainty, even before money shows up.

The key to unlocking abundance is not in chasing more—it’s in BEING more.

The Law of Assumption: Believe It Into Reality

The Law of Assumption states that whatever you assume to be true—consciously or unconsciously—will manifest in your reality. Your external world is simply a mirror of your internal beliefs.

    • If you assume life is hard, it will be.
    • If you assume money is difficult to earn, it will be.
    • If you assume things always work out for you, they will.

Most people were programmed from childhood to believe that success requires struggle. They grew up hearing things like:

    • “Money doesn’t grow on trees.”
    • “You have to work hard for every dollar.”
    • “Only lucky people get rich.”
    • “It’s selfish to want more money.”

These beliefs limit your ability to receive. But the truth is:

    • Money is energy. It flows to those who are open to receiving it.
    • Wealth is an extension of your self-worth.
    • You don’t have to earn abundance—you just have to align with it.

Rewire Your Money Beliefs

If you want to attract more financial abundance, start by shifting your assumptions:

    • Assume money comes to you in expected and unexpected ways.
    • Assume opportunities for wealth are everywhere.
    • Assume financial success is your natural state.

The moment you believe that money is easy, limitless, and always flowing to you, your reality will rearrange itself to match that belief. Let go of the old programming and assume your wealth into existence.

Healing: The Key to Unlocking Your Freedom

Abundance isn’t just about money. It’s about feeling whole, worthy, and complete within yourself.

Your financial reality is a reflection of your inner world. If you have unresolved trauma, deep-seated fears, or limiting beliefs, they will show up in your relationship with money.

Healing is the key to stepping into your highest potential. Until you face your wounds, they will continue to write the script of your life, keeping you chained to the past.

How Trauma Blocks Abundance

When you’ve experienced hardship, your nervous system holds onto that energy. If you grew up in scarcity, your body might still be operating from survival mode, constantly fearing that there’s not enough.

Signs Your Trauma is Affecting Your Money:

    • Fear of spending money, even when you have it.
    • Feeling guilty for receiving wealth.
    • Undercharging for your work because you don’t feel “worthy” of more.
    • Attracting financial instability or unexpected expenses.
    • Believing you must struggle to succeed.

To step into true abundance, you must heal the subconscious wounds keeping you in scarcity.

Abundance: A State of Being

Abundance is not just about financial wealth—it is an energetic state of being that flows through every aspect of life.

    • It exists in the love we give and receive.
    • It exists in the creativity we express.
    • It exists in the health we nurture.
    • It exists in the wisdom we gain.

Abundance is everywhere. It is in the air we breathe, the endless possibilities before us, and the deep knowing that we are always supported.

To live abundantly, you must embody it. When you think abundantly, speak abundantly, and act abundantly, you attract abundance in all forms.

Affirmations for Abundance

Speak these affirmations daily to shift your mindset:

    • I am limitless, ever-expanding, and abundantly supported in all ways.
    • Everything I desire flows to me effortlessly and naturally.
    • Money, love, and opportunities come to me in expected and unexpected ways.
    • I trust the universe, and I trust myself.

The more you assume abundance, the more you will see it manifest in your life.

You don’t need to chase money.
You don’t need to struggle.
You don’t need to earn your worth.

You just need to BE in alignment with the truth:

You are already abundant.

Step into your power, trust the flow, and watch your reality transform. You were never meant to live in scarcity. You were meant to overflow.


Strategies for Cultivating Financial Abundance

Unlocking financial abundance requires a multifaceted approach that goes beyond mere monetary strategies. Individuals can raise their money set point by raising their vibratory frequency to enhance their adoption of a mature and professional financially manifestational mindset.

The following methods to increase your money frequency are often overlooked yet offer valid positive vibrational impact that effectively raises one’s money set point frequency. These will assist you in your quest to gather principles for manifesting abundance, incorporating elements of self-awareness, financial responsibility, and personal growth.

1. Mindful Wallet Management:

    • Adopting a disciplined approach to the visual representation of one’s wallet is an often overlooked detail in attracting abundance.
    • Consider using a wallet in colors associated with prosperity, such as gold or green, to symbolize wealth.
    • Maintaining an organized wallet with denominations stacked in order with bills facing the same direction exemplifies your newfound respect for money.
    • Incorporating tangible reminders, like keeping unused $100 bills tucked within, where they can be easily seen or not, just knowing that they are there can create a sense of financial security.

2. Balancing Intimacy and Prosperity:

    • Recognize the interconnectedness of personal relationships and financial success.
    • Quality intimate sexual relationships, whether with a partner or oneself, contribute to a positive mindset, raising one’s vibrational frequency, which fosters financial abundance.
    • Encourage individuals to evaluate the quality of their relationships and consider how these dynamics may impact overall life satisfaction, as not well nor deeply connected partners may reduce your financial vibration.

3. Crystals for Abundance:

    • Crystals, such as citrine and ametrine, are believed to harness energies conducive to wealth manifestation.
    • Integrating crystals into a professional space, charged under the full moon, can serve as a subtle yet effective tool for fostering abundance.
    • Affirmations, combined with crystals, offer an additional layer of positive reinforcement.

4. Overcoming Dream Obstacles:

    • Avoid prematurely dismissing dreams as too expensive without conducting proper research.
    • Encourage individuals to explore the actual costs of their aspirations before deeming them unattainable.
    • Develop a proactive approach to realizing dreams, utilizing tools like price alerts and focused intention.

5. Empowering Hands for Prosperity:

    • Acknowledge the role of hands in creating and receiving wealth.
    • Regular self-care practices, such as manicures, symbolize respect for one’s ability to generate income.
    • Incorporate scents associated with abundance, like sweet orange oil, into hand care routines.

6. The Power of Asking:

    • Emphasize the importance of effective communication in manifesting desires.
    • Encourage individuals to practice assertiveness in various aspects of life, including financial negotiations.
    • Create awareness around language use, steering away from disempowering phrases like “I can’t afford that.”

7. Self-Worth and Financial Abundance:

    • Challenge the belief that self-worth is solely determined by financial status.
    • Foster a positive self-image independent of monetary wealth.
    • Highlight the liberating impact of separating self-worth from financial net worth.

What About My Credit Score?

In contemporary financial management, the significance of credit scores and conventional banking-influenced investment strategies cannot be denied. However, a counterintuitive perspective suggests that these concepts may hinder efforts to raise one’s money vibration and alter one’s money setpoint.

1. Credit Score and Money Vibration:

    • The Illusion of Wealth:
      • Relying heavily on credit can create an illusion of wealth without genuine financial substance. This artificial sense of affluence may contribute to a misalignment between one’s perceived and actual financial status.
    • Debt-Driven Stress:
      • Even with a good credit score, accumulated debt can induce stress and anxiety, negatively impacting your overall well-being. Elevated stress levels counteract the positive energy required to raise your money vibration.
    • Limiting Beliefs:
      • A fixation on maintaining an exceptional credit score might lead to limiting beliefs about the necessity of debt for financial success, obstructing a mindset shift towards abundance and prosperity.


2. Cash Spending and Attracting Abundance:

    • Tangible Wealth Accumulation:
      • Spending cash instead of relying on credit allows for tangible wealth accumulation. Physically handling money can reinforce positive feelings of abundance, fostering a more favorable money vibration.
    • Reducing Financial Stress:
      • Cash spending eliminates the burden of debt, reducing financial stress and contributing to an environment that encourages a positive relationship with money.
    • Manifestation through Abundance:
      • The conscious choice to spend cash is aligned with the principles of manifestation, affirming a belief in abundance and attracting more positive financial energy.

3. Balancing Credit Use and Cash Spending:

    • Strategic Credit Utilization:
      • While a good credit score has merits, strategic credit utilization is advised for significant investments or emergencies. The key is not to become overly reliant on credit for daily expenses.
    • Mindful Cash Spending:
      • Incorporating mindful cash spending for routine expenses reinforces a conscious and intentional approach to financial management.

Conclusion:

In the pursuit of elevating your money vibration and altering your money setpoint, a mature and professional approach integrates self-awareness, responsible financial practices, a nuanced approach to credit and cash, and personal growth in pursuing financial abundance. 

While maintaining a good credit score is beneficial in certain scenarios, the deliberate use of cash for routine spending can contribute significantly to fostering a positive money mindset. Balancing credit use with mindful cash spending allows for a holistic financial strategy that aligns with the principles of abundance and manifestation, ultimately attracting more positive financial energy into your life.


A Brief Look at T. Harv Eker’s 6 Money Jar Management System

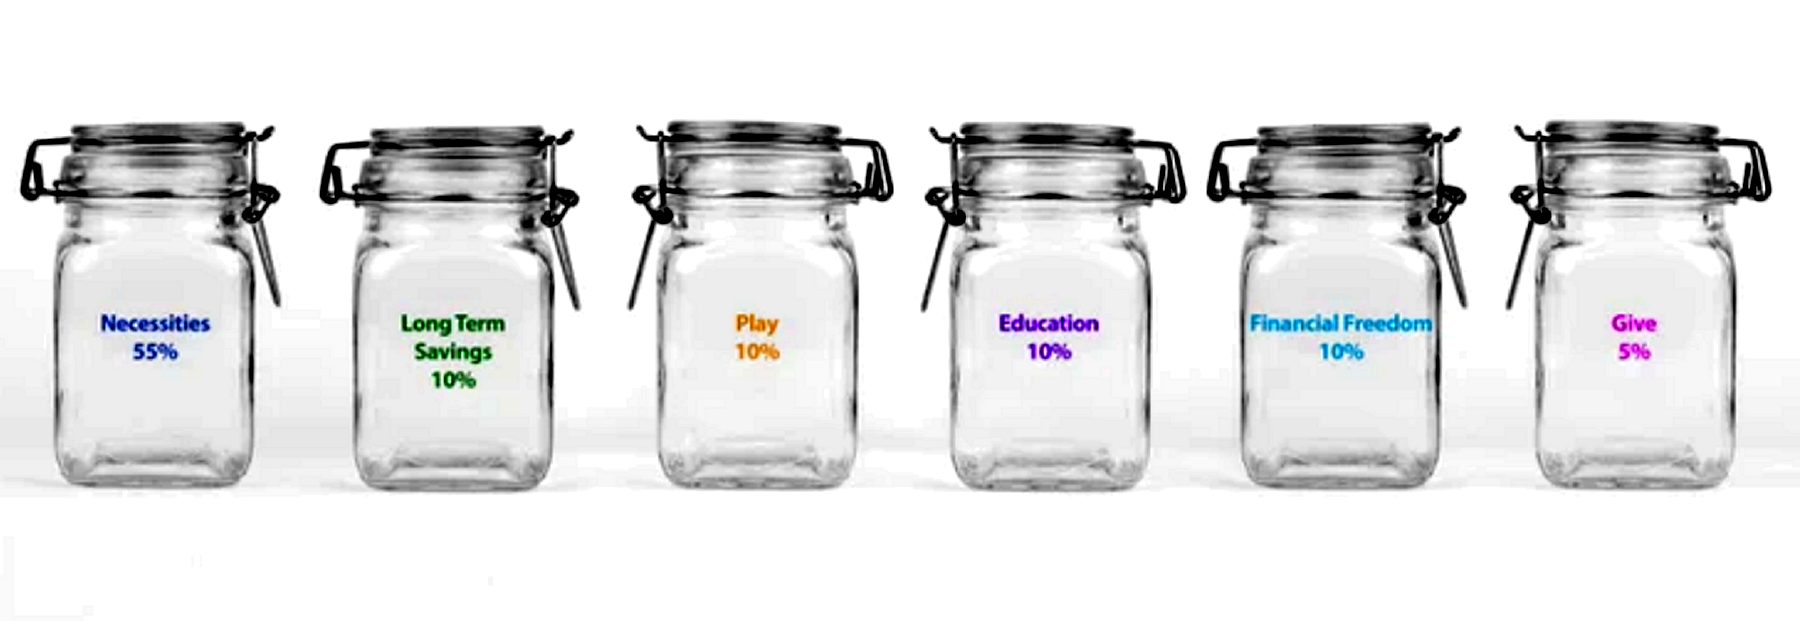
Achieving financial success is not merely about making money; it’s also about managing it wisely. T. Harv Eker introduced a powerful financial management system, the 6 Money Jar Method, designed to bring clarity and purpose to your income distribution.

This simple method uses six jars, each labeled for its use and comes with a percentage of your net income designated for a particular purpose. While on the surface it may sound highly restrictive, it is a disciplined approach to help you budget while looking after your financial big picture. And if that is beginning to sound highly restrictive, don’t panic. While there are jars for the usual things that you might expect to hear from a money manager, note there are jars for “Education,” “Giving,” and surprisingly, “Play.”

Yes, while it is essential to learn money management skills to raise your money frequency, having fun is just as important as any part of your money vibration. In this way, you help to reset your money setpoint.

This system is divulged as a method of using six physical jars, which could be the starting point to get you into the habit of separating your money into different amounts for specific purposes; you can understand that this translates into using six different bank accounts just as easily, each one with its own debit card used for specific purposes.

  1. Jar 1: Necessities (55% of Your Income):
    • Allocate 55% of your income to cover essential expenses vital for your family’s well-being.
    • Examples include food, shelter, transportation, utilities, and recurring bills.
    • Set Aside: $55.
  2. Jar 2: Long-Term Savings For Spending (10% of Your Income):
    • Dedicate 10% of your income to building a financial safety net for emergencies and significant purchases.
    • Examples encompass a rainy day fund, emergency medical expenses, and savings for a home down payment.
    • Set Aside: $10.
  3. Jar 3: Play (10% of Your Income):
    • Designate 10% of your income to indulge in activities that bring joy to you and your family.
    • Examples involve treating yourself to fancy dinners, spa days, travel adventures, or attending concerts.
    • Set Aside: $10.
  4. Jar 4: Education (10% of Your Income):
    • Devote 10% of your income to continual personal and professional growth.
    • Examples range from investing in books, courses, coaching, to mentoring opportunities.
    • Set Aside: $10.
  5. Jar 5: Financial Freedom (10% of Your Income):
    • Set aside 10% of your income to pave the way for financial independence through passive income streams.
    • Examples include investments in stocks, mutual funds, real estate, affiliate marketing, and automated business ventures.
    • Set Aside: $10.
  6. Jar 6: Give (5% of Your Income):
    • Allocate 5% of your income for philanthropy, supporting causes that uplift and educate others.
    • Examples involve contributions to non-profits, faith-based groups, NGOs, or assisting personal contacts in need.
    • Set Aside: $5.

Note that of all the jars, the one labeled PLAY must emptied and spent every month on fun stuff that brings you joy and happiness. As you raise your money frequency and reset your financial setpoint, this jar or account raises in relation to the others as well. Think about what this jar will look like when you add a zero to it and later adding another zero.

This is the abundance mindset. Imagine having to spend the current amount with two additional zeros added every month just for you to enjoy all the nice things this world has to offer. That is an abundance that is worth moving toward as you start to attract more financial abundance.

Your FINANCIAL FREEDOM jar is not for speeding. It is not for put-and-take money but is reserved for put-and-keep money. Money that is set aside for investing only. This is for investing to generate a greater financial profit. As the profits from your investments come in, they are redistributed as new income throughout the jar system, and so, your net worth grows, further raising your financial set point.

Conclusion:

T. Harv Eker’s 6 Money Jar Management System provides a holistic framework for managing your finances, ensuring that your income serves various aspects of your life purposefully. By implementing this system, you secure your financial stability and nurture personal growth, joy, and a commitment to giving back to the community. Consider customizing this system to align with your unique financial goals, fostering a balanced and prosperous life.

References:

This JARS Money Management System Can Work Miracles For You

Transforming Self-Perception: The Path to Abundance Strategy

Developing an abundance mindset begins with reshaping how we perceive ourselves, identifying and dealing with money blocks, and creating new habits to replace limiting beliefs that do not support our best financial interests. By understanding and changing personal beliefs, individuals can pave the way for a life and business characterized by abundance.

The Self-Perception Exercise:

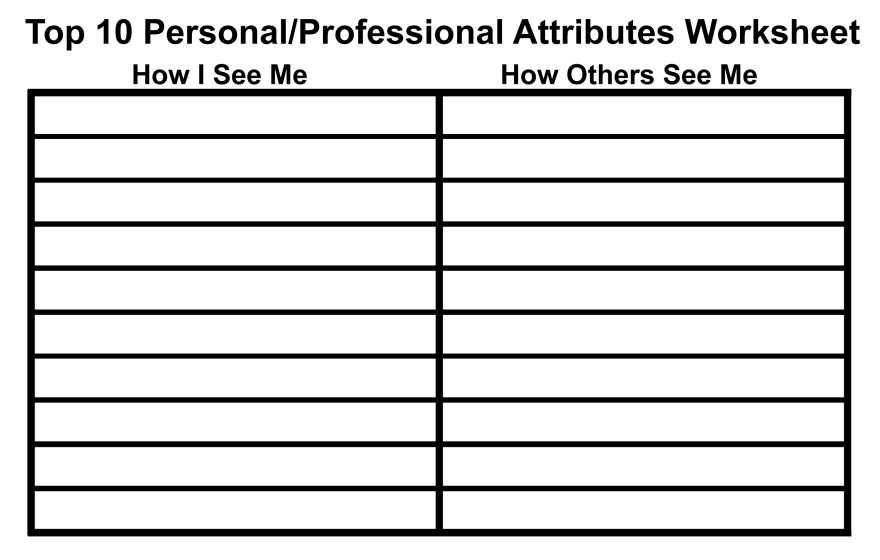
To initiate a shift toward an abundance mindset, start by creating a T-chart: one side detailing the ten best attributes from your point of view as a person or business person. On the other hand, outline the ten best things about you from the point of view of others.  To better understand how others might see you, seek input from close friends and family to compile a list of their perceptions. This exercise unveils the alignment or discrepancies between self-perception and who you are known as or external perception, offering valuable insights for personal growth.

Once you have completed this assignment, you will be able to increase your congruency by creating a map of attributes that you will need to focus on exemplifying in such a way as to be better perceived by others.

Oprah Winfrey

Like Oprah Winfrey:

Examining the experiences of successful individuals like Oprah Winfrey, who underwent transformative self-awareness journeys, underscores the importance of aligning personal beliefs with external perceptions. Winfrey’s commitment to self-reflection and authenticity contributed to her success, highlighting the impact of a positive self-view on achieving abundance. These examples emphasize the significance of self-awareness in pursuing an abundance mindset.

Identifying Money Mindset Blockages

Exploring the intricate landscape of your money mindset reveals many limiting beliefs that hinder your financial growth. Recognizing these money blocks is the first step towards dismantling them and fostering a mindset conducive to financial prosperity. Here are the ten most prevalent mindset blocks surrounding money, providing insights, debunking myths, and offering strategies for overcoming these barriers.

    1. Money is the root of all evil“: Debunking the myth that money is inherently evil, this mindset often stems from misconceptions. In reality, money serves as a neutral medium of exchange. Its impact depends on the individual wielding it. Acknowledging this can empower individuals to utilize money positively and effect meaningful change.
    2. I can’t afford it“: Financial constraint often serves as an excuse, limiting creative problem-solving. This mindset hinders the exploration of alternatives and inhibits the pursuit of valuable investments, such as coaching or courses.
    3. It’s selfish to want more money.” Contrary to this belief, having financial stability enables individuals to make a more significant impact on their communities. By challenging this mindset, one can unlock the potential to contribute to causes that matter and extend assistance to those in need.
    4. I’m not good with money“: Perceiving oneself as incapable of financial management is a disempowering narrative. Financial literacy can be acquired like any other skill, and dispelling this myth opens the door to developing new skills for effective money management.
    5. My family has never been rich“: Breaking free from the narrative that family history dictates financial success is essential. Numerous stories of individuals rising from poverty to wealth emphasize the potential for personal agency in economic matters.
    6. It is selfish to want money“: This mindset challenges the idea that financial success and selflessness are mutually exclusive. More resources can amplify one’s capacity to contribute to causes that align with their values, benefiting personal and communal well-being.
    7. I can either make money or do what I love, not both.” This dichotomy neglects the symbiotic relationship between passion and financial success. One can bridge the gap between personal fulfillment and financial gain by aligning one’s passion with solving problems and providing valuable services.
    8. Money is there to spend“: While spending itself is not inherently negative, prioritizing spending over saving and investing poses challenges. Balancing enjoyment and financial responsibility is crucial for long-term prosperity.
    9. You have to work really hard to get money“: While effort is required, the belief that earning money demands unbearable hardship is a limiting mindset. Embracing strategies to solve problems efficiently and scale efforts can lead to financial success without undue strain.
    10. Money is not that important“: Acknowledging the importance of financial stability does not diminish life’s other priorities. Recognizing money’s role in making life more manageable fosters a proactive approach to financial control.

By unraveling these most common money mindset blocks, individuals can pave the way for a more empowered and prosperous financial journey. Challenging these limiting beliefs opens the door to financial growth, enabling individuals to take control of their economic well-being and contribute positively to the world around them.

While each person has accumulated a lifetime of limiting beliefs and money mindset blocks, most people will find three or more of these top 10 in their psyches. This is an excellent place to start.

Warren Buffett

Addressing Specific Mindset Issues:

Identifying and addressing specific mindset issues, such as a reluctance to invest in one’s business due to fear or pessimism, is crucial. Drawing on examples of successful entrepreneurs who shifted their mindset around investing, like Warren Buffett, highlights the transformative impact of embracing optimism and intelligent business decisions. Changing one habit or mindset issue at a time can lead to significant positive outcomes.

Transforming self-perception is a foundational step toward living a life of abundance in both personal and business domains. The exercise provides a roadmap for individuals seeking to align their beliefs with positive external perceptions. By understanding the role of habits and committing to gradual change, individuals can break free from limiting beliefs and embrace life and business characterized by abundance.

Dr. Maxwell Maltz

Data-driven Insights on Habit Formation:

Research in psychology, such as studies conducted by Dr. Maxwell Maltz, reveals that habits play a pivotal role in shaping our beliefs and behaviors. The exercise of identifying and reshaping self-perceptions aligns with habit change principles. By acknowledging negative thought patterns and working to transform them, individuals can pave the way for lasting change and a mindset of abundance.

The 21 to 30-Day Habit Formation Window:

Studies suggest that creating a new habit takes approximately 21 to 30 days. Focusing on one aspect at a time, such as overcoming a scarcity mindset related to time constraints, enables individuals to instill positive habits gradually. By consistently chipping away at negative thought patterns, the path to success becomes more apparent, as demonstrated by individuals who have successfully transitioned from scarcity to abundance thinking.

With these three techniques—evaluating and adjusting how we are perceived in the world, identifying and dealing with money blocks, and creating new habits to replace limiting beliefs that do not support your best financial interests—you can change your financial journey from one of drought with challenges to one of financial abundance.

References:

    • Winfrey, O. (2021). Biography.
    • Maltz, M. (1960). Psycho-Cybernetics. Prentice Hall.
    • Buffett, W. (2023). Biography